All Categories
Featured
How to Compare 2026 Medicare Advantage Options in Los Ang...
Top Health Insurance Enrollment Trends for Residents in Y...
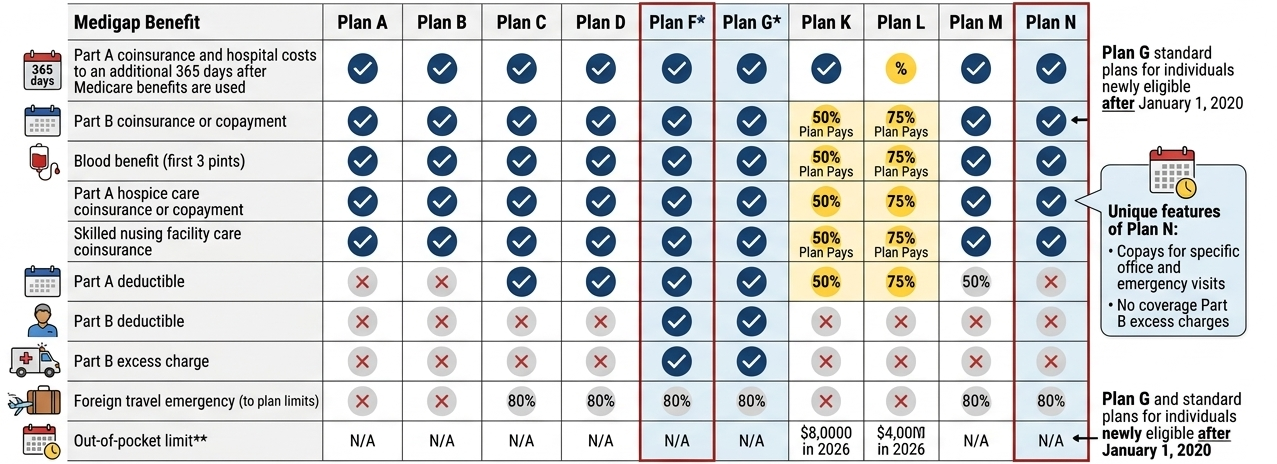
Evaluating Medicare Supplement Plans for Optimal Coverage
PPO vs HMO Health Insurance Options
Table of Contents
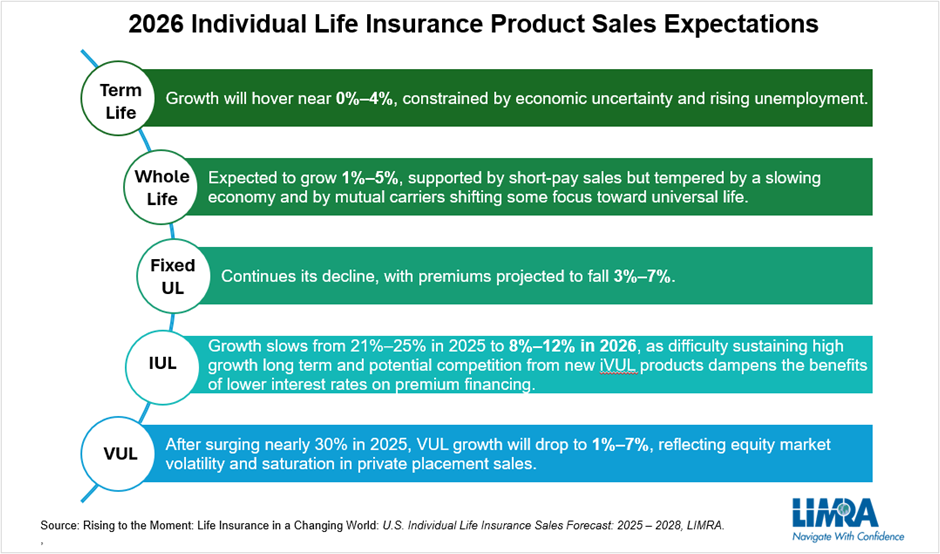
You are paying for permanence and ensured money value, not just a survivor benefit. Larger entire life policies scale up roughly in proportion to the face amount. If your goal is pure income replacement, term life provides far more protection per dollar; if your goal is guaranteed irreversible coverage regardless of the length of time you live, whole life is constructed for that.
Below are normal term life rates for seniors a $250,000 10-year term policy (male, non-smoker): AgeMonthly PremiumAnnual Cost60$70$84065$120$1,44070$210$2,52075$380$4,560 The majority of carriers cap term length as you age a 20-year term is commonly offered at 60 however rarely at 70. Match the term to a particular requirement (a staying home mortgage, a spouse's earnings space).
A single regulated condition (blood pressure, cholesterol) has a bigger dollar effect at 65 than at 35. A professional broker helps you find the carrier that treats your health most favorably. For a much deeper breakdown, see our devoted guides for life insurance over 50 and life insurance over 60. This is the most affordable time to buy, even if your protection needs are modest.
Comparing PPO vs HMO Health Coverage
You can constantly include more protection later. SituationRecommended CoverageMarried, kids, home loan$750K-$1.5 MSingle parent$500K-$1MHigh earner ($150K+)$1.5 M-$3MPersonal + crucial person protection 20-year level term if your kids are young.
Numerous obligations are at their peak. Home mortgage is developed, kids are growing, and college is approaching. SituationRecommended CoverageKids heading to college in 5-10 years$500K-$1M (match to staying years)Big home loan remainingCoverage matching balanceApproaching peak making years10-15x income 15 or 20-year level term. If you currently have a 30-year term from your 30s, you might have enough.
Kids might be independent, home loan is shrinking, and retirement cost savings are growing. SituationRecommended CoverageMortgage almost paid offReduce protection or keep for income replacementKids independentCoverage need drops significantlySpouse depends on your incomeMatch to years until retirementFinal expenses just$25K-$50K irreversible policy 10-year term for particular requirements, or final expense entire life for irreversible protection.
Life Insurance Solutions for United States Veterans
Here is the true cost of procrastination: Buy at AgeMonthlyTotal Over 20 YearsExtra Expense vs.
And that assumes you stay healthy. What is the best age to purchase life insurance coverage? The best age is as young as possible.
A 25-year-old pays roughly half what a 35-year-old spends for the exact same protection. Buying in your 20s locks in the most affordable rate for the longest duration. How much does life insurance coverage increase by age? Rates increase about 8-10% annually in your 20s-30s, 10-15% annually in your 40s, and 15-20% per year in your 50s-60s.

Why to Use IUL for Retirement Planning
Is it too late to purchase life insurance coverage at 60? What are whole life insurance rates by age? Entire life is a number of times more costly than term since the protection is long-term and develops cash value.
See the entire life chart below. What are typical life insurance rates for seniors?
Rates increase steeply with age, so using faster instead of later matters most in this bracket. See personalized rates from leading providers in minutes. Compare rates from top life insurance coverage providers. No medical examination choices readily available.
PPO vs HMO Health Insurance Plans
Term Life insurance is an essential monetary tool that offers comfort and monetary security for your loved ones. Understanding can be a bit complicated. In this short article, we'll break down the numerous aspects that influence life insurance costs, how much you can expect to pay, and pointers for getting the finest rates.
The buying a 20-year term policy for $250,000 in coverage. for the same coverage. looking While the. Term Life insurance is often referred to by other names, such as "instantaneous life insurance" or "no test life insurance coverage." These terms describe various kinds of term life insurance policies. Life insurance tends to be more expensive than disability insurance due to the fact that it offers a death benefit to recipients, which can be a considerable quantity of money.

Latest Posts
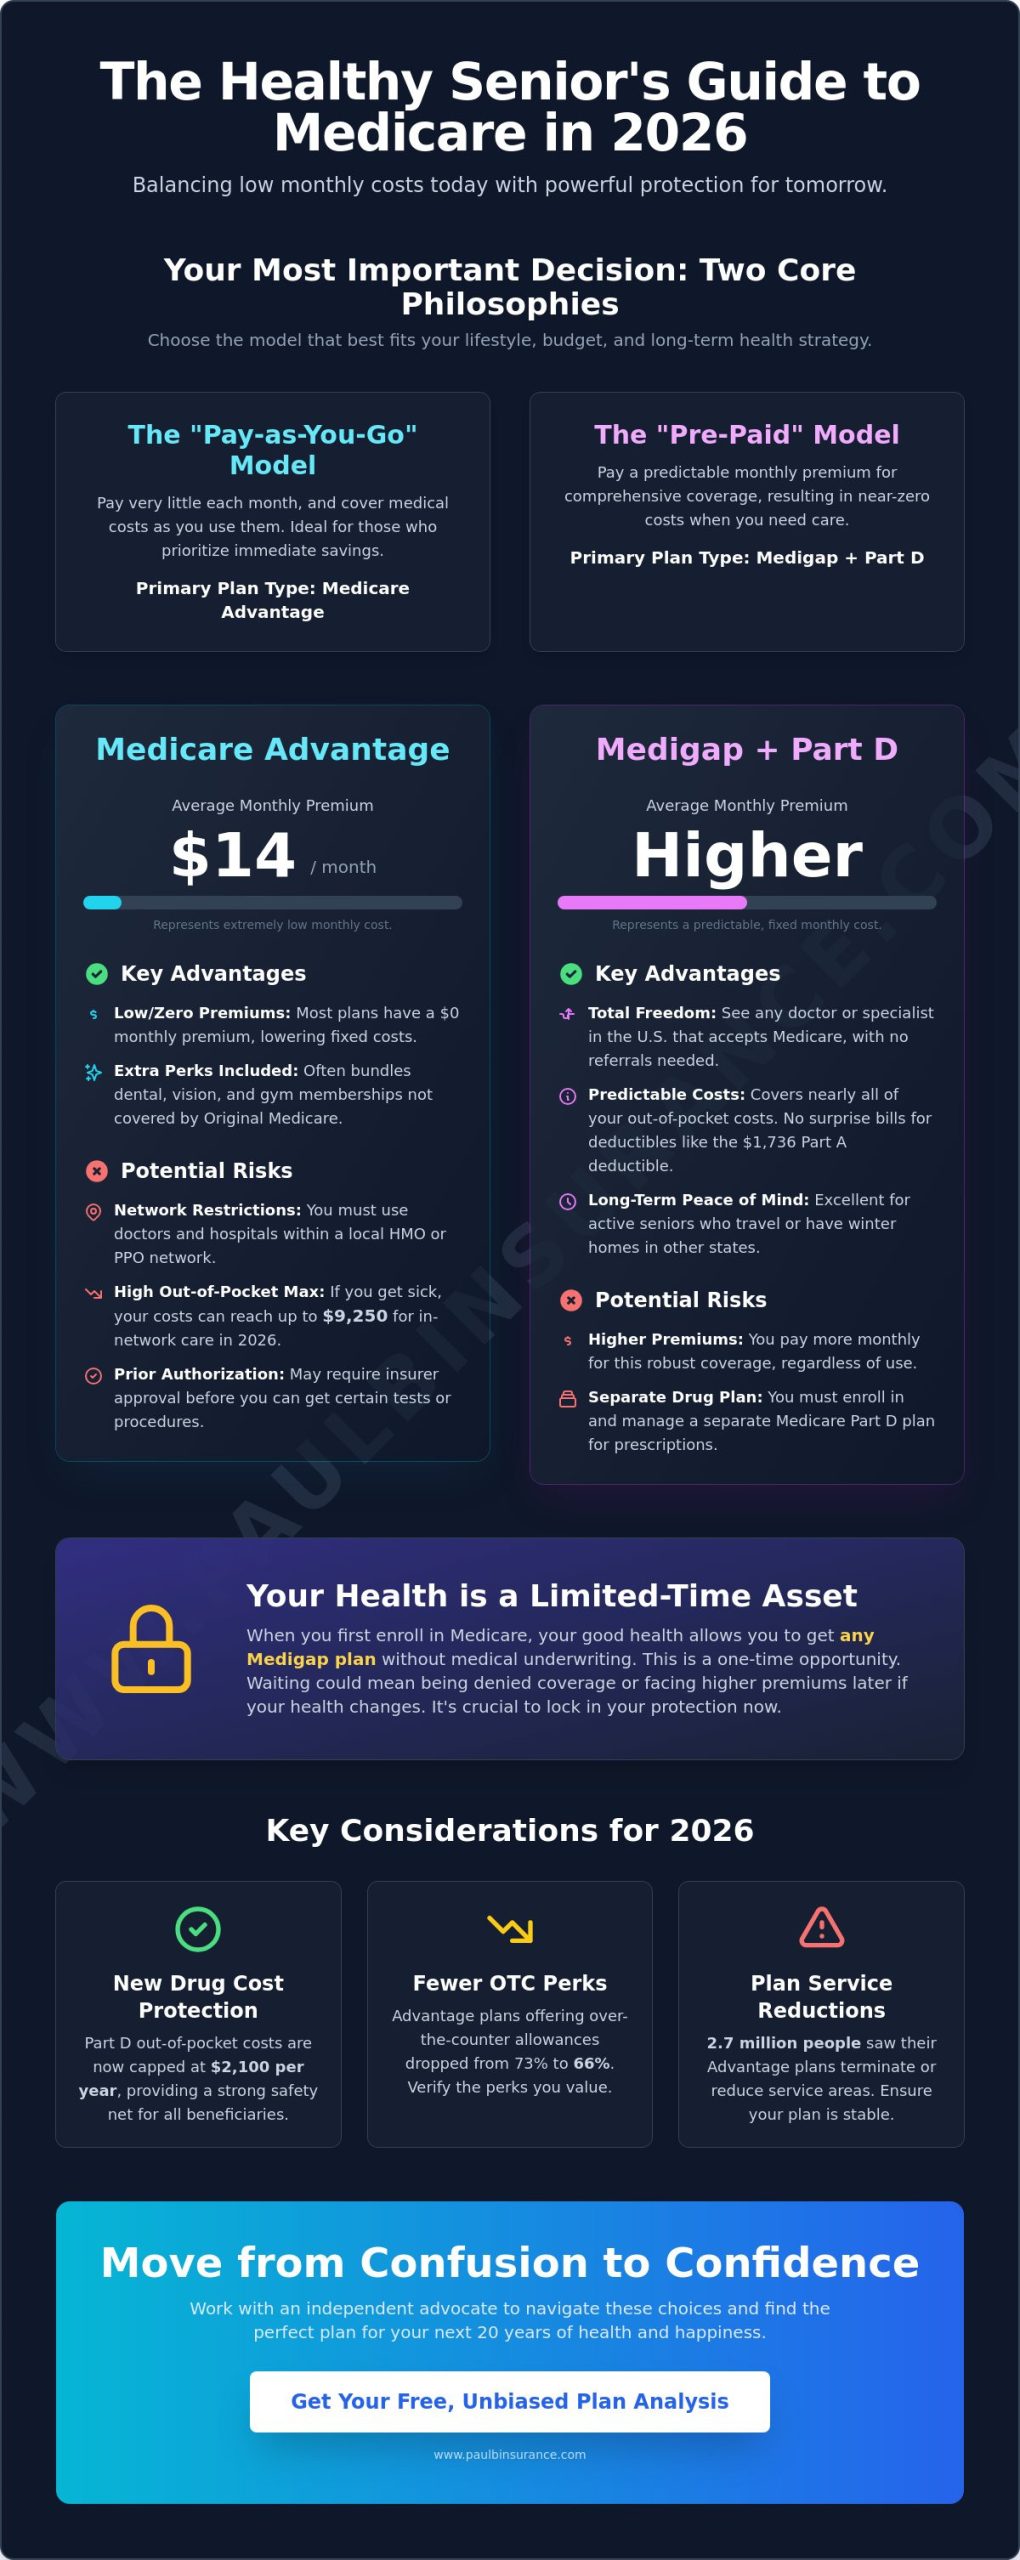
Finding Cheap Family Medical Insurance
How to Compare 2026 Medicare Advantage Options in Los Angeles

Top Health Insurance Enrollment Trends for Residents in Your Area